
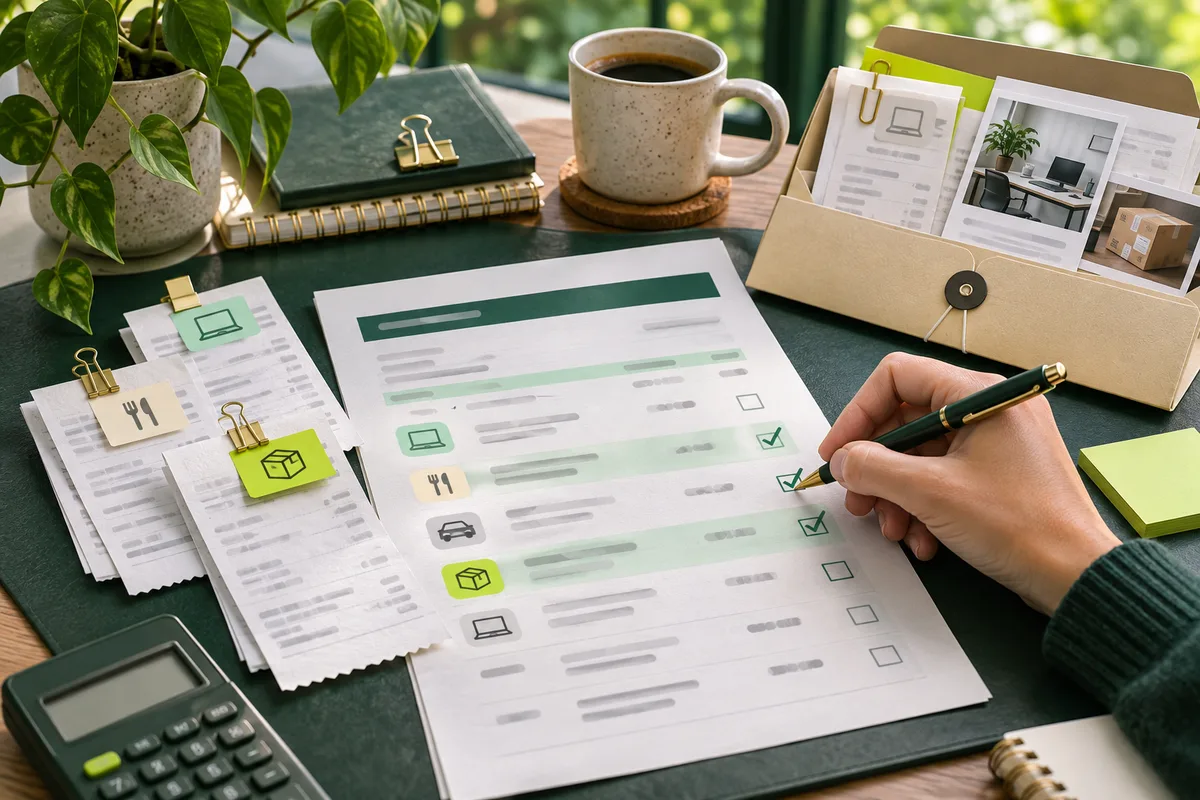
Start with a potential-expense queue
Identify likely business or tax-related debits as candidates, not conclusions. Retain merchant, date, value, payment method, bank description, proposed category, and evidence status.
Bring related refunds, credits, and reimbursements into the same review. Considering only the debit can inflate net cost and disconnect later corrections from their original transaction.
Create an expense-candidate queue before deciding tax treatment. Preserve bank description, date, value, account, proposed category, missing support, and status for each row. An office-supplier card charge may deserve investigation, but it does not reveal purchased items, purpose, sales-tax detail, returns, or personal use; the queue directs evidence gathering rather than creating a deduction.
Build a candidate queue without assigning final treatment from the merchant name. Record source description, date, amount, account, possible category, missing evidence, and review status. A payment to an office supplier can still include personal goods, a refundable deposit, or items returned later. The statement cannot show the itemized purchase or business purpose. Use the queue to request the supporting records and apply current jurisdiction-specific guidance, not to convert every familiar business merchant into an automatic deduction.
Collect evidence that explains the purchase
Require a receipt or invoice that identifies supplier, goods or service, date, and amount. If that document does not establish business purpose, add a specific contemporaneous explanation.
For contractual or subscription charges, keep the agreement and covered billing period. When a cash receipt is unavailable, create a prompt record of the facts and then apply the requirements of the relevant jurisdiction.
Link refunds and reimbursements to the original candidate before calculating any supported amount. A later credit may reduce cost, reverse the purchase, or represent an unrelated receipt. Preserve both source rows and the evidence for the relationship so the review does not claim a gross expense after part or all of it was returned.
Expense substantiation worksheet
An item should enter final tax totals only after its required evidence fields are complete.
Payment
Capture the exact bank row together with every linked refund, credit, or reimbursement.
Supplier evidence
Attach itemized proof, such as a receipt, invoice, or agreement, showing what was purchased.
Purpose
Record the precise business or other eligible purpose while the underlying facts remain available.
Allocation and review
Preserve mixed-use calculations and identify the person or authority supporting the treatment.
Handle mixed-use and shared payments
When only part of a payment may qualify, preserve the full source value and separately document the allocation method, supported portion, personal portion, and calculation.
Merchant identity alone rarely resolves marketplace, travel, telecommunications, home, or vehicle claims. Use itemized invoices, usage evidence, logs, or applicable professional guidance.
For mixed use, retain the whole payment and the supported allocation method. If a 240 invoice contains personal goods worth 90 and documented business supplies worth 150, keep the 240 bank row, itemized invoice, supported 150, excluded 90, and explanation together. Changing the source amount to 150 would break reconciliation and conceal the personal portion.
Preserve the full payment when allocating mixed use. If a fictional 240.00 invoice contains 150.00 of documented business supplies and 90.00 of personal goods, retain the original bank row, itemized bill, accepted 150.00 share, excluded 90.00 share, and reasoning as one linked set. Never replace the posted payment with only the supported share. Doing so breaks reconciliation and removes the personal part that explains why the source payment exceeds the selected amount.
Preserve review decisions
Record the decision as accepted, adjusted, excluded, or referred for professional review, and preserve its reason. Do not include unresolved candidates in final totals before their treatment is supported.
This process organizes evidence; it does not decide deductibility. Because treatment depends on facts, jurisdiction, tax year, and taxpayer circumstances, material positions should be checked against current official guidance.
Close candidates with explicit statuses such as supported, partly supported, excluded, duplicate, refunded, or missing evidence. Cite the authority or professional instruction for jurisdiction-dependent treatment. Year-end totals should include only completed reviews and reconcile to preserved payments, creating an evidence trail without treating the statement as automatic proof of deductibility.