
Bank Statement Cash Flow Summary
Preparing your private analysis
Your statement is being secured before analysis begins.
Leave this window open; your private results will load here when ready.
Build a traceable cash-flow summary from verified rows by separating external credits and debits, owned transfers, refunds, exceptional movement, and unresolved entries.
Verified external creditsminusVerified external debitsequalsNet external movement
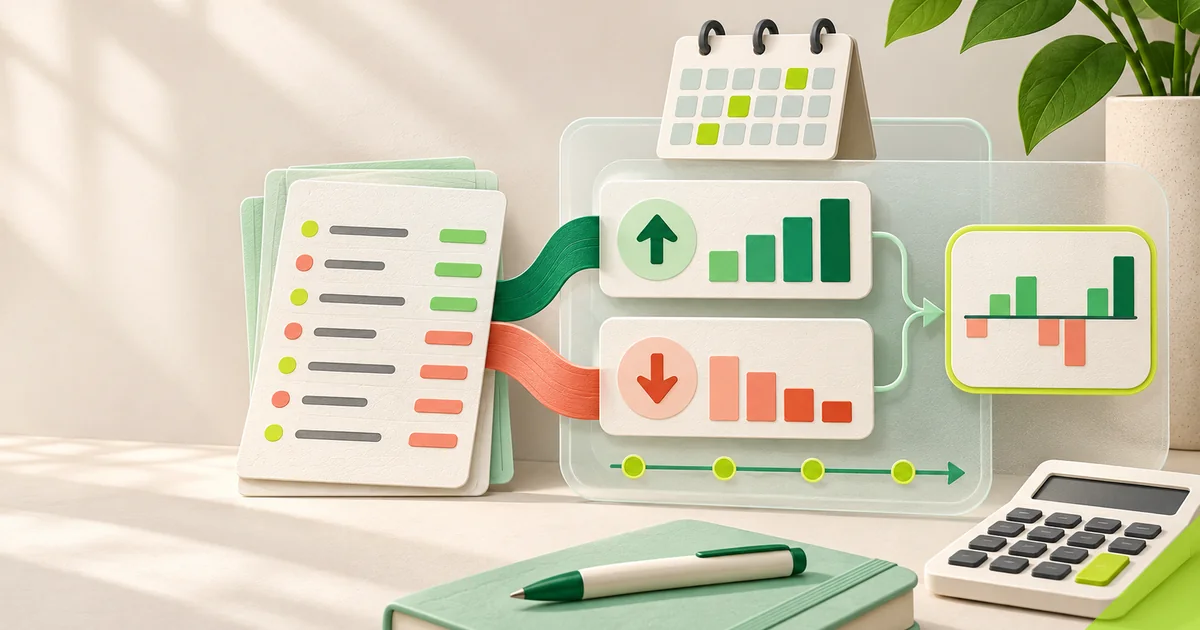
A summary with visible boundaries
The displayed values are imaginary examples, not findings from any uploaded statement.
Define the cash-flow boundary
Define included accounts, currencies, and complete periods, then set treatment for borrowing, owned transfers, gifts, reimbursements, refunds, cash deposits, and owner contributions before calculating totals.
Retain each source row in the ledger even when excluded analytically. Reviewers can then change definitions without losing movement required to reconcile the account.
Calculate totals that can be traced
Total verified external credits separately from debits and derive net movement. Reconcile that result with opening-to-closing change after documented fees, interest, reversals, and corrections.
Place classification coverage, uncategorized value, and open rows beside headline figures. A partly reviewed ledger should not produce a summary that appears fully certain.
Example transfer-adjusted cash-flow summary
Across two included accounts, assume $5,000.00 external credits, $3,600.00 external debits, and a $900.00 checking-to-savings transfer. Pairing the transfer prevents it from appearing as new income and outflow, leaving $1,400.00 net external movement.
Keep both transfer postings visible in their ledgers and account views, excluding them only from consolidated external totals. Document the pairing rule and send any unmatched candidate to review.
Summary release conditions
- Define included accounts and complete periods
- Remove both sides of owned transfers
- Reconcile movement with printed balances
- Report uncertainty, timing, and concentration
Add timing and concentration
Because monthly totals conceal interim shortages, examine major inflow timing, required payment dates, verified minimum balances, and gaps between dependable income and obligations.
Show each leading spending group and income source as a share of the relevant defined total. A short observation period describes history and cannot establish stable future income or a forecast.
Extend the cash-flow review
Cash Flow Analysis from Bank Statements
Cash flow describes funds moving through an account, but transaction direction does not establish economic purpose. Credits are not automatically income, and debits are not automatically expenses.
Compare Bank Statements Month to Month
Month-to-month conclusions require stable scope and definitions. Unequal period lengths, absent accounts, or changing transfer treatment can manufacture an apparent trend.
Bank Statement Income Consistency
Consistency is demonstrated over complete periods, not inferred from every credit. First separate transfers, refunds, borrowing, and one-time receipts from qualifying inflow.
Understand the calculation of totals
Review how the method handles credits, debits, transfers between owned accounts, reconciliation, timing, concentration, and unresolved entries.