
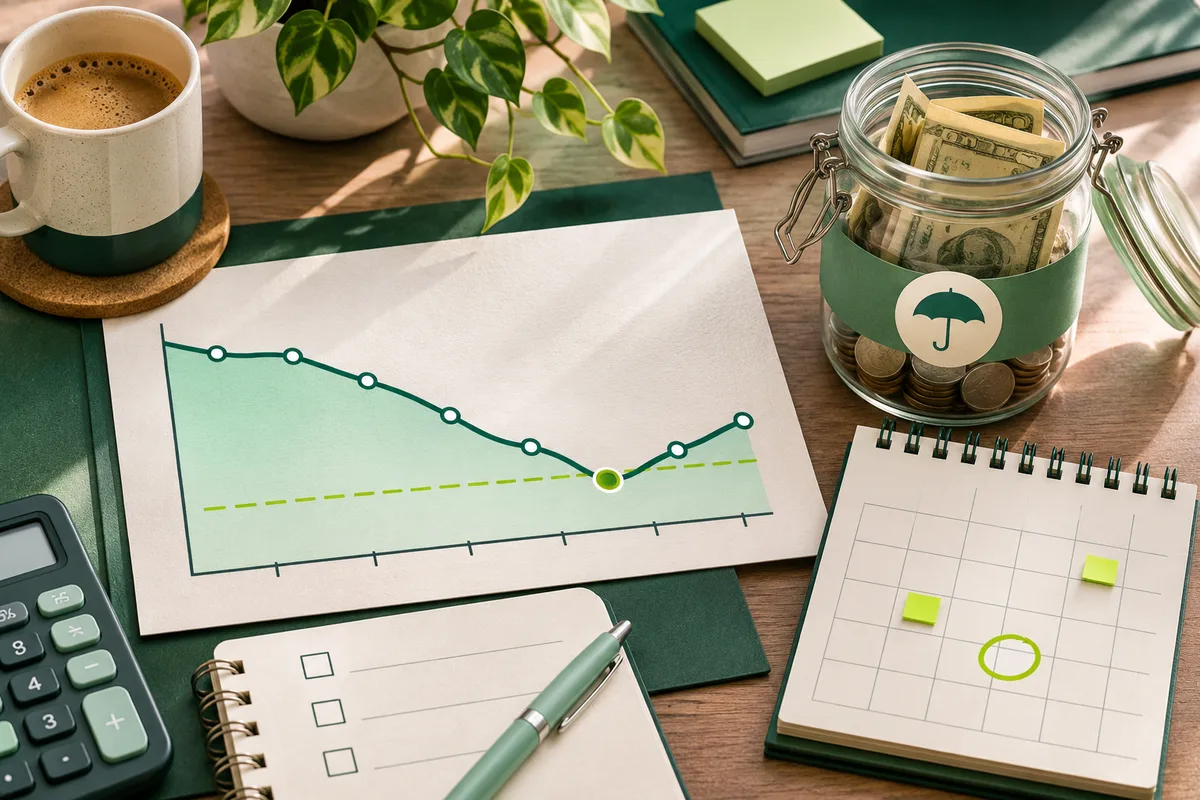
Validate the balance series
Verify the opening balance and all transactions used in reconstruction, using printed running balances wherever available. Do not claim an intraday minimum from same-day entries unless timestamps or documented bank ordering support their sequence.
Keep available and ledger balances conceptually distinct from pending items, holds, and any overdraft facility. Issued statements usually show posted activity and may not reveal the funds available at every moment.
Choose a meaningful threshold
Set the threshold at zero, a personal reserve, or the amount needed for identified obligations before the next dependable inflow. Disclose both the chosen level and its rationale; no single number is universally safe.
Measure days below the threshold, the longest continuous stretch, the verified minimum, and obligations due within each window. Several periods are needed to distinguish recurring timing pressure from an isolated month.
Run the same history against at least two disclosed thresholds when the decision is sensitive to the chosen level. A zero-balance test reveals direct shortfall risk, while an obligation-based threshold shows how often committed payments would leave too little room for ordinary variation. Report both outcomes rather than presenting one threshold as an objective health score.
Expose the reserve calculation. If required payments of 680 and 420 precede a reliable 1,600 inflow, a verified pre-payment balance of 850 leaves a 250 gap before variable spending or timing delay. Test a 250 minimum plus a disclosed margin, but do not call it universally safe because obligations, overdraft rules, and income reliability vary.
Make the threshold visible. If verified required payments of 680.00 and 420.00 fall before the next reliable 1,600.00 inflow, while the balance before those payments is 850.00, the observed shortfall is 250.00 before variable spending or timing delay. One scenario may therefore use 250.00 plus an explicitly disclosed cushion, without presenting the result as safe for everyone. The threshold depends on the obligations, account rules, income reliability, and period being studied.
Low-balance analysis output
Preserve these fields so another reviewer can reproduce the result and compare later periods.
Threshold
Record the minimum selected and the evidence connecting it to the planning purpose.
Exposure
Report low-balance day count, longest run, and lowest verified closing value.
Timing drivers
Identify verified income and required payments immediately around every low-balance window.
Scenario
Calculate one proposed date, value, or reserve change while clearly labeling it as a scenario.
Separate amount problems from timing problems
When a positive-ending month dips before income arrives, scheduling may be the primary pressure. When verified recurring outflows repeatedly exceed inflows, changing payment dates cannot remove the underlying shortfall.
Test one intervention at a time, such as moving a due date, splitting a payment, reducing discretionary spending, or increasing the reserve. Treat changed provider terms as hypothetical until the provider confirms them.
Distinguish verified end-of-day evidence from assumed intraday order. When five transactions share a date and only one daily close is printed, report that close and, if needed, a possible range rather than a precise minimum. Also state the balance measure because fees, holds, and pending card activity may affect availability without posting as rows.
Distinguish ledger evidence from available-funds risk. A printed running balance can reproduce posted activity but may not include card authorizations, deposit holds, or an overdraft facility shown in an online available balance. Name the balance used and observation time. If several transactions share one date without timestamps, report the verified daily close and any possible range instead of inventing a precise intraday low. This keeps a buffer analysis from claiming more timing precision than the statement provides.
Build the buffer from observed pressure
Anchor the reserve to the largest recurring gap between verified inflow and required outflow during low-balance windows. Add an explicit margin for variable costs or delayed income instead of selecting an unsupported round figure.
Hold the reserve in a form available for its intended use and recalculate it when income timing or required payments change. This method supports planning; it is not individualized financial advice.
Check the proposed buffer against weekends, bank holidays, posting delays, and the longest observed gap between dependable deposits. Keep an overdraft limit outside the reserve calculation because borrowed capacity is not cash on hand. Record the period reviewed so a later update can show whether the pressure pattern actually changed.
Present the output as scenario analysis. Show how low-balance days change with another threshold, a one-day inflow delay, or an early required payment, and retain the selected threshold, period, missing days, and exclusions beside the result. Buffer discussion should begin with these sensitivities and verified obligations, not a universal household multiple.