
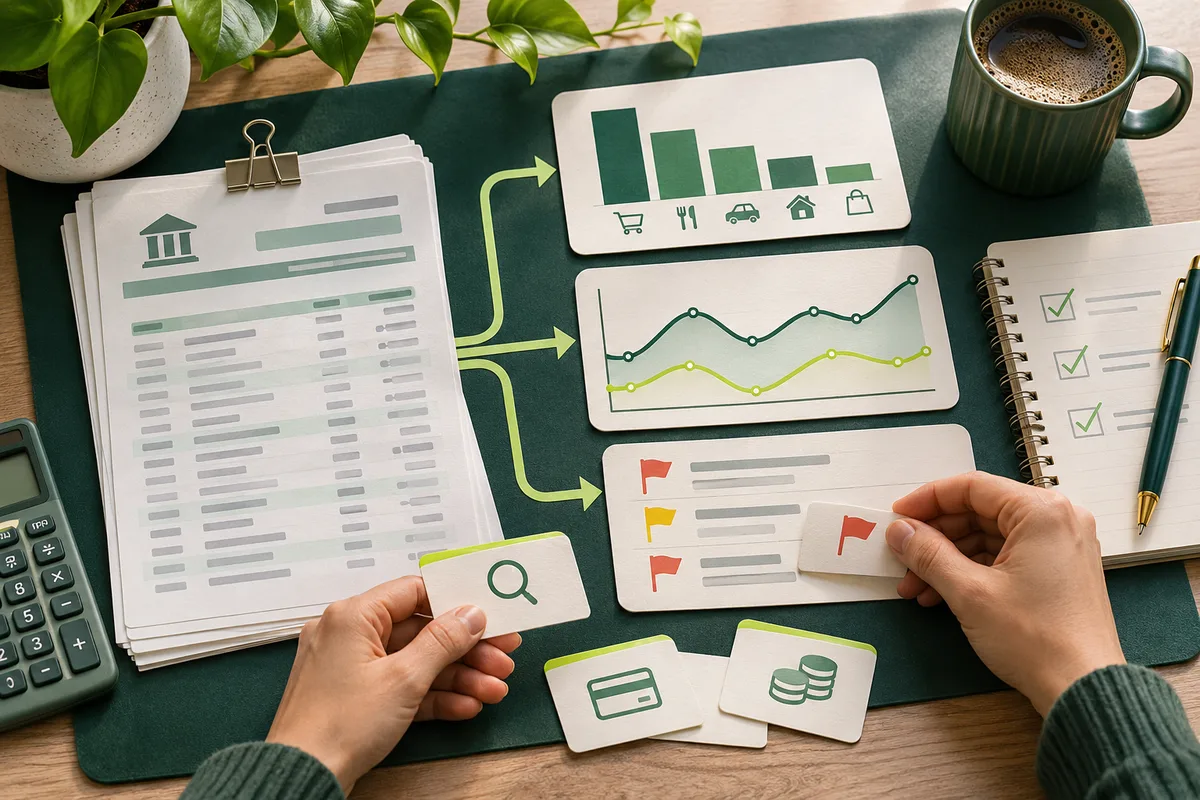
Construct a ledger that remains tied to the document
Represent each posted entry once and preserve its exact description. Put standardized values in additional fields so the evidence remains available. Useful columns include posting date, any value date, source wording, normalized merchant, debit, credit, running balance, proposed category, and reviewer note.
Store the covered dates and statement currency at the document level. Where several currencies appear, retain each original figure with its currency apart from any conversion.
Minimum analytical data dictionary
Set these definitions before consolidation so every statement period is evaluated consistently.
Transaction direction
Document the meaning of a positive value, and retain distinct debit and credit fields where possible.
Transfer rule
Define the proof required to identify owned-account transfers and remove them from consolidated income and expense totals.
Category rule
Specify the evidence behind category assignments and the transaction types that cannot bypass review.
Confidence rule
State the criteria for high, medium, and review-required confidence in both extraction and interpretation.
Prove the ledger totals before drawing conclusions
Total incoming and outgoing entries separately, then compare your calculated close with the document's closing balance. Any gap can point to a missing or duplicated row, fees, interest, or a figure assigned to the wrong column.
Running balances offer an independent test. When every balance after one entry is off by an identical figure, inspect that entry for a structural mistake. Intermittent gaps instead suggest reversals or same-date ordering issues.
Use three independent controls when possible: printed period totals, opening-to-closing movement, and running-balance continuity. Agreement on only one control is weak. A duplicated debit and a duplicated credit of the same amount could leave net movement unchanged while inflating both cash-in and cash-out totals. Row counts and independent debit and credit totals expose that error. Store the result of each control with the data release so a later chart can be traced to the exact version of the ledger that passed review.
Calculate cash movement without counting owned transfers twice
Distinguish outside income and costs from transfers among your accounts. Show credits, debits, net change, significant incoming and outgoing entries, and what portion of debits has a reviewed classification.
One month documents only that interval and cannot demonstrate a durable pattern. Questions about seasonality or dependable income require multiple full periods measured under consistent rules.
Show how certain each inferred result actually is
Classifications and recurring matches are interpretations rather than source facts. Include a review status or confidence field and disclose the rule used. A merchant recurring at comparable amounts, for instance, suggests a pattern but does not confirm a current subscription.
Avoid manufactured certainty. When the image leaves a digit unclear, mark the entry for review instead of guessing from neighboring patterns. Base practical decisions on details checked against the source.
The release summary should separate verified evidence from derived fields and count source, reconciled, and unresolved rows, manual and rule-based categories, recurring candidates, and excluded transfers. Identify every output affected by open values. A reader can then accept a usable cash-flow total while leaving merchant comparison under review instead of judging all analysis as entirely valid or invalid.
Publish uncertainty at the level where it exists. If one merchant name is unclear but its amount and direction are verified, the period balance can still reconcile while the merchant analysis remains incomplete. If one amount is unreadable, totals that depend on that row should remain provisional. A useful release note names the unresolved field, affected outputs, excluded value, reviewer action, and evidence needed for closure. This is more informative than assigning one confidence score to the entire statement and hiding which conclusions are safe to use.
Keep bank evidence separate from analytical judgments
Build one layer that mirrors the statement, including posting date, verbatim description, page, row sequence, debit, credit, and balance. Put merchant normalization, categories, transfer links, recurring groups, and confidence in another layer, allowing later judgments to change without altering the evidence.
Track review state explicitly, for example unreviewed, confirmed, corrected, or excluded with a stated reason. When an amount changes, retain both the extracted and verified values and cite the evidence behind the correction.
Check how dependent the result is on definitions
Challenge the result by varying one rule, such as removing internal transfers, treating refunds apart from income, or leaving cash withdrawals unallocated. If that choice materially changes the outcome, disclose the dependency instead of presenting a single figure as settled.
Compare periods only when their coverage is complete. An incomplete month may understate spending, exaggerate income variation, or overstate liquidity because a major payment date falls outside the data.
When working from a scan or a photo taken by phone, start with the bank statement image reader and keep each uncertainty alert next to the field it concerns.