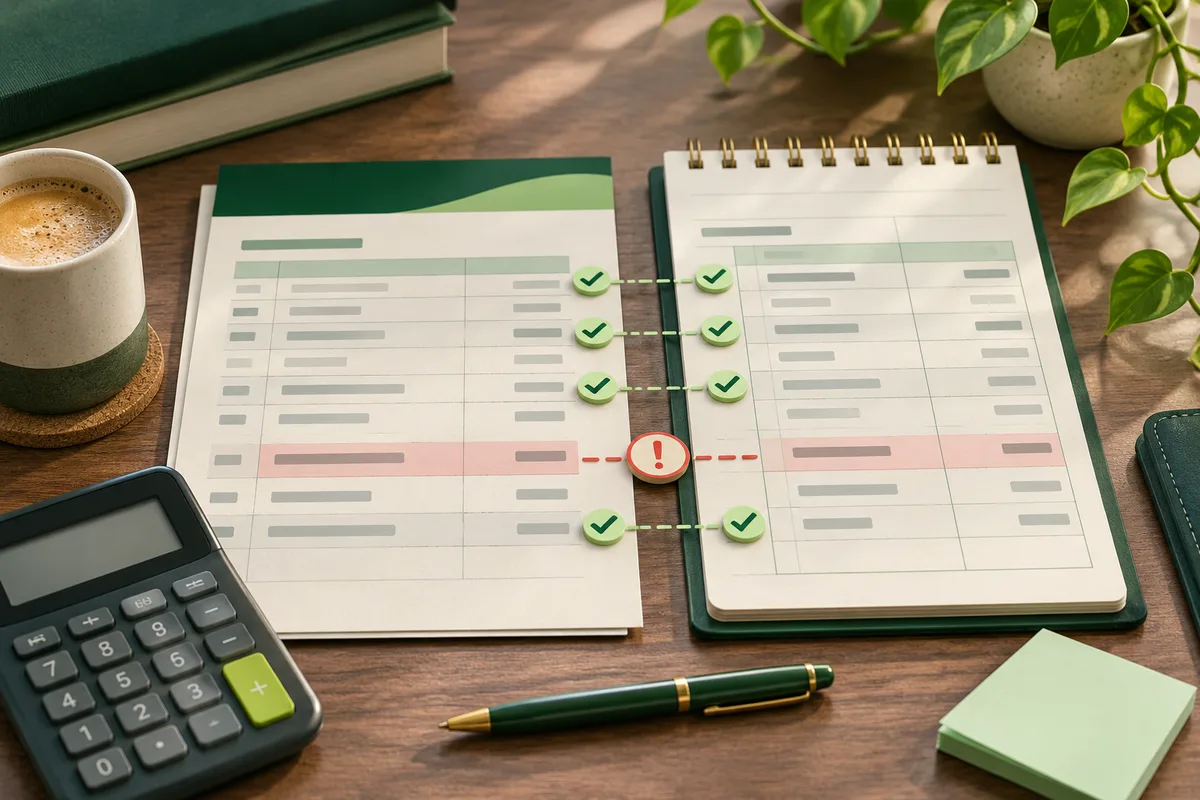
This illustration uses imaginary information. Check actual statement details directly against the source.
Apply the same closing date to both records
Set both sides to the statement's closing date. Activity beyond that cutoff belongs in a later reconciliation, even when online banking already displays it.
Pair incoming and outgoing entries using supporting context
Dates alone are insufficient for matching; compare figures and identifying details. Weekends, settlement delays, and deposit batches commonly move posting dates.
Record unresolved timing items in a separate schedule
Checks that have not cleared and deposits still in transit belong on the reconciliation, not in altered statement data.
Reconciliation exception log
Keep a separate exception row open for each difference until evidence shows clearance or correction.
Identity
Link the relevant statement row and ledger entry with the date, amount, and matching reference.
Difference type
Classify the issue as timing, fee, interest, return, duplicate, omission, incorrect value, or unresolved.
Required action
Assign responsibility for obtaining support, recording an adjustment, or contacting the bank.
Closure evidence
Cite the later statement, receipt, correction posting, or institutional response that closes the exception.
Enter adjustments only after confirming them from evidence
Books may need updates for statement fees, interest, returned items, or direct debits not previously entered. Cite the statement and keep its reference with the adjustment.
Keep a reconciliation schedule
The reconciliation schedule should expose book and bank balances, deposits and payments still outstanding, items found in only one record, errors, and the adjusted totals. For each difference, record its date, value, explanation, evidence reference, and expected clearing period.
Let control totals identify which record needs attention
When the statement proves its own movement but disagrees with the books, review ledger entries and cutoff treatment. When extracted rows fail to reach the printed closing balance, correct the extraction before any ledger comparison.
For row-level matching in a spreadsheet or ledger, export a reviewable bank statement CSV and retain the original descriptions.
Bank records and books view one account through separate systems. A defensible match uses the same cutoff, linked evidence, and a schedule for genuine timing differences.
Money that moves between owned accounts or corrects an earlier event needs an explicit relationship. Verify those links before relying on income and spending totals.
More than a purchase list, a statement records activity within fixed dates. Begin with its identity, test the balance calculation, inspect the ledger, and finish with notices.
Apply this guide to a statement
Move statement rows into spreadsheets, accounting software, or independent analysis while retaining a clear path back to the document.