
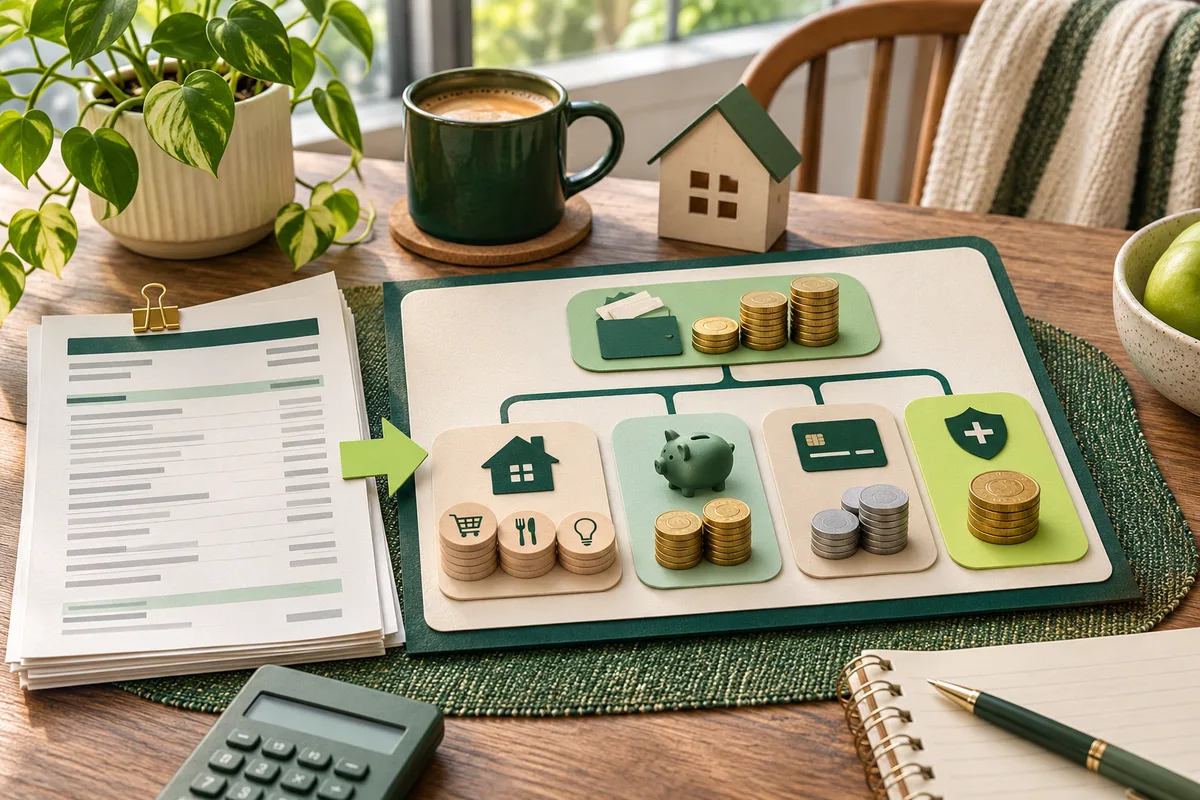
Define what the snapshot includes
Define the accounts and periods before calculating anything, then list owners, currencies, and complete coverage dates. Explicitly include or exclude savings, credit cards, cash, investments, loans, and joint accounts.
Display missing accounts and periods next to the results. A narrow account view can support decisions, but it cannot be represented as a complete household assessment.
State the boundary at the top of the snapshot: accounts included, statement periods, currencies, missing records, transfer rule, category coverage, and unresolved values. A checking account alone cannot describe cash held elsewhere, unpaid obligations, investments, or activity in another household member's account. If the periods differ in length or one statement is partial, show that limitation beside the totals. A bounded view is useful because the reader can see what evidence supports it and what remains outside the analysis.
Build a transfer-adjusted activity view
Verify ledger rows and link transfers among included owned accounts. Report external inflow and outflow, net movement, major sources and categories, refunds, fees, and exceptional items.
Do not blend borrowing, reimbursements, gifts, asset sales, or transfers into recurring earned income. For cash-flow planning, distinguish debt payments from purchases as well.
Start the activity view with external movement. An 800 transfer from included checking to included savings is one owned movement, not 800 of expense plus 800 of income. Link both rows, retain them in account ledgers, exclude them from consolidated external totals, and keep unmatched candidates visible because account gaps or date shifts can distort the snapshot.
Pair owned-account transfers before measuring external movement. If checking sends 800.00 to savings and both statements are included, those two postings represent a single movement between owned accounts rather than separate spending and income. Preserve the two ledger entries and connect them, while removing the matched pair from consolidated outside-account movement. Leave uncertain transfer matches in view: incomplete account coverage, settlement lag, fees, or unequal values can block a reliable pair and materially alter the snapshot.
Add obligations and liquidity
For each recurring candidate, show observed value range, interval, latest occurrence, and confirmation status. An unverified pattern must not be presented as a binding future payment.
Include opening, closing, and minimum verified balances, low-balance days, and inflow or spending concentration. Those measures expose timing pressure that category totals can hide.
Place timing evidence beside category totals: minimum verified balance, days under the selected reserve, major external inflow dates, and required recurring outflow dates. Even 1,200 of positive monthly net movement can coexist with a pre-payroll low week. Show the ending result, the path producing it, and days that cannot be reconstructed from available balances.
Add timing to the category summary. Capture the smallest confirmed balance, count of dates beneath the selected reserve, dependable income dates, and required-payment dates. Positive movement of 1,200.00 at month-end can coexist with several strained days just before pay arrives. Link each proposed action to the source rows that produced it, such as confirming one recurring candidate or reviewing a fee. The snapshot should end with traceable questions, not generic financial advice or a claim that one statement reveals a complete plan.
Snapshot output sections
Keep the summary concise for decisions while retaining enough references to reproduce every result.
Coverage
Identify accounts, currencies, covered periods, missing records, and unresolved extraction exceptions.
Activity
Show external inflow, expenditure, net change, transfers, refunds, fees, and exceptional movement.
Patterns
Report verified categories, recurring candidates, source concentration, and required-payment timing.
Liquidity and limits
Expose balance pressure, uncategorized value, uncertain entries, exclusions, and priority actions.
Finish with limitations and actions
Quantify uncategorized value and identify unreadable entries, absent support, uncertain transfer pairs, and incomplete periods. Explain which reported results those limitations could change.
Select a few traceable follow-ups, such as verifying a recurring charge, obtaining a missing statement, investigating a fee, or reviewing a low-balance interval. The evidence supports those observations, not universal financial advice.
Conclude with a short action register tied to evidence, such as confirming an unknown recurring candidate, obtaining a missing statement, investigating a fee, or reviewing a low-balance window. Link every action to source rows and periods, identify missing evidence, and track status. The snapshot reports observed activity and is not a complete financial plan.